News & Views arrow
September 29, 2026

For Startup Founders: Your Financial Model is Much More than a Revenue Projection

Every founder raising venture capital will be asked to walk an investor through a financial model. But what is the investor actually looking for? Erin Crowther breaks down how an investor evaluates the assumptions, the output, and the capital ask, and why the founders who can explain the logic connecting all three earn the most confidence.

If you are a startup CEO seeking venture capital, you will inevitably be tasked with providing and explaining your financial model to investors. We all have our strengths, and – for some – this can be a daunting exercise. While you don’t necessarily need to be the modeling guru, it’s critical that you know how your model is built, what drives it, what story it tells, and what it takes to get there.

However, nailing the revenue projection is only the starting point. At its core, the model is the financial translation of your business strategy.

Understanding how an investor approaches the model can help you come to the table more prepared. Below are three foundational assessments of the model that an investor often works through: the assumptions, the output, and the capital story.

1. The Assumptions: How your model is built

This is the section of the model that drives everything else, and is often where an investor will start. The assumptions will consist of foundational beliefs about your business and communicate how the business scales.

  • What drives your revenue?

Your business model determines what drives revenue, and that connection should be clear in your financial model. For example, a SaaS company’s revenue could be tied to sales capacity and therefore additional sales hires. In an equipment sales model, sales could be tied to expanding production capacity. For a marketplace, it may be unlocking more supply-side liquidity. Investors should be able to quickly identify what needs to happen for sales to grow and why you believe that growth is achievable.

  • What is your pricing model?

Beyond the price point itself, your pricing model will communicate assumptions about how, when, and on what basis customers pay you. Do you charge per seat, based on usage, as a percentage of value delivered, or per transaction? As a customer’s consumption grows, how does your price scale in response? Do customers pay a monthly recurring fee, annually upfront, or per-transaction? These foundational assumptions demonstrate how you capture the value you bring to customers and when cash flows into your business.

  • What is your cost structure?

These assumptions show the necessary resources it will take to run your business and how costs scale over time. This includes variable and fixed costs – such as salaries, marketing spend, or cost of goods sold. Which costs stay flat regardless of volume, and which increase directly with production, headcount, or revenue?

  • How does the team grow?

The hiring plan shows your assumptions about the skill sets and headcount needed as the company moves through different growth phases. Beyond when you hire, it estimates how long it takes for a new hire to be fully productive, and the fully loaded cost of that role, once benefits and overhead are included.

Investors evaluate hundreds of financial models and will never know as much about your business as you. It’s key that your assumptions are well organized and easy to follow for someone who doesn’t know your business as intimately as you do. A simple, yet effective, tool is to provide a short model narrative stating your key assumptions, how you determined them, and which ones you still need to validate.

2. The Output: Your financial profile

The output shows what your assumptions produce, including revenue growth, margins, and cash burn. This is where an investor steps beyond learning how the model is built and starts assessing the company’s potential, what supports the projections, and how sensitive the company is to changes in key assumptions. Depending on the stage of the business, assumptions range from unproven to verified by actual results, and the less proven they are, the harder an investor will test the numbers.

  • What do your growth curve and metrics actually show?

Before testing whether the projections are credible, an investor first wants a clear read on the financial profile itself. How fast is revenue growing, what shape does that growth take – linear, accelerating, decelerating? Does gross margin improve, hold steady, or erode as the business scales? What happens to cash burn? These outputs aren’t judgments on whether the plan is realistic; they’re simply the picture the model is painting. That picture should be internally consistent and tie back to your assumptions. A growth rate that accelerates should have a clear driver behind it, and a margin profile that improves should tie back to the economies of scale or pricing power you’ve assumed elsewhere in the model.

  • How much confidence can an investor place in a growth curve built from assumptions?

There is no question that the further out the years go, any model is truly a “projection.” That being said, there needs to be some basis in fact. For example, if you have a pipeline of deals that close throughout the year, build the forecast from your funnel, weighted by likelihood and timing, rather than taking a percentage of the total market and hypothetical growth rate. This is also where your unit economics get tested against the story you’re telling. Metrics such as customer acquisition cost, payback period, and margin should hold up at the pace of growth you’re projecting, not just at today’s scale. A model can show a great top-line curve, but if the underlying economics don’t hold as the business grows, that growth becomes more expensive.

  • What happens if the plan is wrong?

The reality is that things rarely go exactly as planned. A downside case is helpful for investors to stress test the model, as this will show how sensitive the business is to changes in key assumptions. For example, what happens if your sales cycle is extended by four months and / or your input costs are higher than anticipated? Investors aren’t looking for a business with no risk, they want to see that you understand what the key risks are, what they mean for your business, and how you would adjust in the event of challenges.

As the company develops, there will be more historical performance to calibrate your model, and the confidence an investor places in your projections should rise accordingly. But even a business that looks good on paper isn’t automatically a venture investment. That judgment depends on what it takes to get there, and whether the terms of the ask make sense given everything the output just showed.
3. The Capital Story: Evaluating your ask

This is where an investor evaluates not just whether the business could work, but whether it’s worth funding right now and whether the amount of capital you’re raising makes sense.

  • Does your capital raise give you enough time to hit key milestones?

An investor wants to see how much you’re raising, how it will be spent, and what this new capital “buys.” The raise should fund the company through value-creating milestones that mark a real de-risking event. Depending on the business, that could mean validating the technology at the next scale, such as moving from batch to continuous production, converting a pilot into a paying customer, demonstrating repeat sales, or proving that unit economics hold as production scales. This is the progress and proof that your foundational assumptions are being verified, positioning the company to successfully raise additional capital.

The raise also must be sized realistically to get you to that point. How much runway does it buy, and does it leave enough time to hit the milestones and raise the next round before cash runs out? A core principle to remember is that venture dollars are meant to be put to work. Sizing a round too tightly forces a founder back into fundraising before the story has meaningfully changed, while sizing it too large without meaningful spending becomes inefficient capital deployment for an investor.

  • Does the ask support a venture return?

Venture capital investors are underwriting the possibility of an outlier outcome, one large enough to make a meaningful difference to their overall portfolio returns. If this capital unlocks the revenue and growth profile the model claims, what does the business look like at exit? At a realistic exit multiple, does that valuation return enough, relative to what was invested? Is the total addressable market even large enough to support a company worth that much? A great business can still be a poor venture investment if the likely exit value and the investor’s ownership don’t leave room for a return multiple large enough to matter.

Together, these three sections summarize how an investor may approach your model: learning what you believe, assessing the financial profile, and determining whether the capital you’re asking for can get to a return. A founder who can walk through all three and explain the logic connecting them comes to the table prepared.

In the end, the model an investor is underwriting isn’t just a set of numbers; it’s a translation of your business strategy. How well you can explain it is often the strongest signal of how well you understand the business you’re building.
News & Views arrow
April 9, 2026

Why We Invested: R3 and the Missing Link in Battery Recycling

HG Ventures recently co-led a major investment in R3 Robotics, a Luxembourg-headquartered company focused on the automated disassembly of end-of-life electric vehicle and other complex electrical systems, at scale. Erin Crowther draws back the curtain on why we are all in on this robotic revolution.

Battery recycling is often framed as a chemistry problem: How do we recover more critical materials? How do we improve yields? How do we make the process more efficient?

But in many cases, the real constraint sits much earlier in the process, at the disassembly stage.

The Hidden Bottleneck

Before any chemical recycling processes can begin, batteries must be safely and effectively taken apart, and that has traditionally been manual, often dangerous work, and difficult to scale.

Battery packs can weigh over 1,000 pounds. They contain high voltages, hazardous materials, and complex assemblies of fasteners, casings, and components. Disassembling them is not only labor-intensive, it also introduces real safety risks.

At the same time, battery designs are constantly evolving, so recyclers are not dealing with a single standardized format, but with a wide, growing and ever-changing variety of pack designs.

While EV batteries are the most visible example, the disassembly challenge applies beyond just them. Many other complex electrical systems—across vehicles, industrial equipment, and electronic devices —share the same characteristics: high voltage, hazardous components, intricate assembly, and significant variability in design. In each case, disassembly is a critical, and often overlooked, constraint.

The result is a bottleneck.

If you can’t safely and efficiently disassemble these systems, you can’t scale recycling. And if you can’t scale recycling, you limit both material recovery and the broader transition to a circular economy.

R3’s Approach: Safety and Throughput

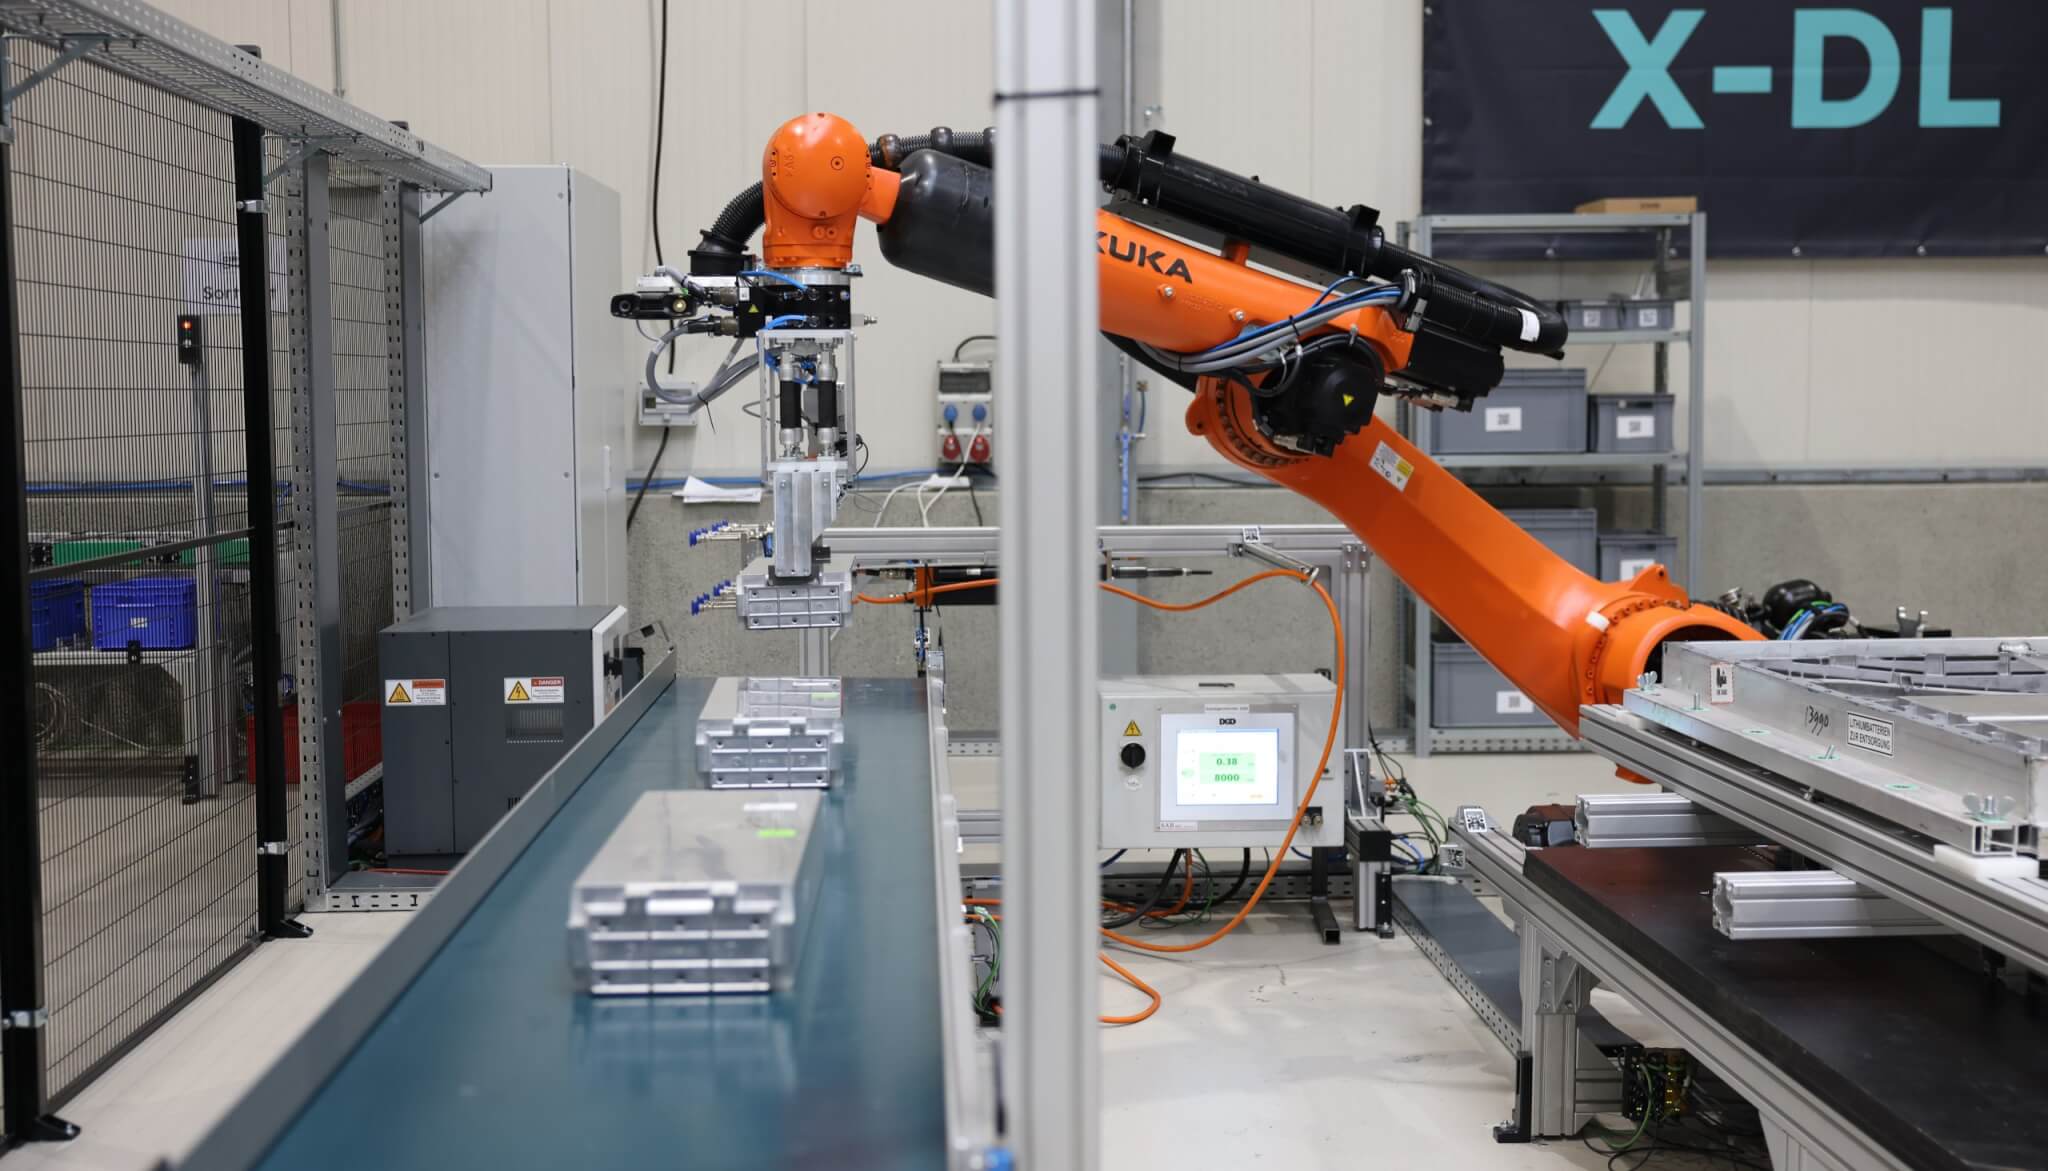
R3 is focused on solving that bottleneck directly, starting with EV battery systems, but with an approach that extends to a broader class of complex electrical assemblies.

At its core, the company is deploying robotics and software to transform disassembly from a manual, high-risk process into one that is automated, safer, and more scalable.

Two outcomes sit at the center of that approach:

  • Safety: Reducing human exposure to high-voltage systems, heavy components, and hazardous materials
  • Time and throughput: Automating (and so speeding up) a process that is otherwise slow, intricate, and labor-dependent

Taken together, those outcomes change the game for EV battery disassembly and recycling.

Why It Matters

When disassembly becomes faster and safer, the impact cascades through the entire recycling process.

  • More systems can be processed: Throughput increases, enabling recyclers to handle growing volumes of end-of-life batteries and other electrical equipment.
  • Material recovery improves: More precise disassembly reduces damage and enables better separation of components, increasing the value of recovered materials.
  • Unit economics strengthen: Lower labor requirements, combined with higher throughput and recovery rates, improve the economics of recycling overall.

In other words, improvements at the front end compound across the entire value chain.

How R3 Makes It Work

What stood out to us is not just the problem R3 is addressing, but how it is doing so.

A modular system, delivered as a service: R3’s technology is designed to integrate into existing facilities, rather than requiring recyclers to build new infrastructure from scratch. Combined with its Robotics-as-a-Service model, this lowers upfront capital requirements, aligns incentives with customer outcomes, and allows customers to scale capacity in line with demand.

A growing data advantage: Battery formats, and electrical system designs more broadly, are rapidly changing across manufacturers and applications. As R3 processes more batteries and other electrical systems, it builds a library of knowledge that allows it to adapt to new designs and improve over time. That feedback loop—more systems, more data, better performance—is central to its long-term differentiation.

Robotics and software built for real-world execution: Unlike traditional automation, which relies on highly controlled, repeatable environments, R3’s system is designed to operate in the variability of real facilities, handling different form factors, conditions, and workflows. This ability to perform reliably outside the lab is critical to scaling in industrial settings.

Why This Team

It is a truism that VCs invest in people, first and foremost, and this is a team that understands both the technical and operational challenges of what they are building.

There is a strong sense of urgency and practicality in how they are approaching the problem, not just developing technology, but making it easy to deploy that technology in real-world environments where it needs to perform.

That combination of technical depth, operational focus, and a clear understanding of the industry is what gives us confidence in this team’s ability to execute.

The Bigger Picture

At HG Ventures, we spend a lot of time thinking about where bottlenecks exist in industrial systems, and often they are not where you might initially expect.

In battery recycling—and increasingly across other complex electrical systems—disassembly is one of those points. It sits upstream, but it shapes everything that follows.

By addressing that constraint and making the process safer, faster, and more adaptable, R3 is enabling higher recovery rates, better economics, and a more scalable path to circularity.

News & Views arrow
September 16, 2025

Resilience Is the New ROI: Why Durable Innovation Matters More Than Ever

Erin Crowther highlights an important lens through which to view investment opportunities. 

Across the sectors we invest in—electrification, construction, mobility, water, and materials—one theme is increasingly clear: resilience.
As natural disasters become more frequent, supply chains grow more complex, and energy systems are pushed to their limits, infrastructure of all types must be built to withstand disruption.

For investors, resilience is now an essential lens for assessing opportunity. At HG Ventures, it’s influencing how we think about long-term value, risk mitigation, and the kind of technologies we want to back.

What Resilience Looks Like in Practice

Resilience takes different forms by sector. In transportation infrastructure, it means roads, bridges, and safety systems that can endure extreme weather events and extended maintenance cycles. In energy, it is grid stability, redundancy, and the ability to operate during power outages or demand spikes. In supply chains, it is robust logistics networks and smart systems that adapt to real-time conditions. And in materials and chemicals, it is durability, sustainability, and product lifecycles that reduce dependence on volatile inputs.

The unifying principle: Systems don’t just function in ideal conditions, they must continue to operate, perform and adapt under stress.

Why Investors Are Paying Attention

Traditional venture investing has often focused on scalability and speed to market, but resilience adds another layer: Can this business or technology withstand pressure—whether physical, financial, or systemic—and continue to deliver value over time?

At HG Ventures, we view resilience as a multiplier of long-term value. A water treatment solution that continues delivering clean water even during periods of scarcity or drought, or a construction material that doesn’t degrade in extreme temperatures, is more likely to scale sustainably. These aren’t just technological advantages—they’re strategic moats.

And for capital-intensive companies operating in highly regulated, mission-critical sectors, resilience isn’t optional. It’s existential.

How Resilience Drives Financial Return

As investors, we need to invest in companies that can deliver financial return. Here’s how resilience can increase enterprise value:

  • Revenue continuity: If a $100 MM-revenue operation increases uptime by just 1%, that’s ~$1 MM incremental revenue annually—often at high contribution margins.
  • Lower lifetime cost: Materials or components that extend asset life defer replacement capex; deferring a $10 MM replacement from today by five years at a 10% discount rate adds ~$3.8 MM in NPV.
  • Maintenance and warranty savings: More durable systems cut unplanned maintenance by 15–30%, reduce warranty claims, and shrink service truck rolls—direct opex savings that widen EBITDA.
  • Regulatory and bid advantage: Many public and industrial buyers now score for resilience; passing those gates with lower total cost of ownership raises win rate.

Resilience Is in Our DNA

This focus aligns closely with the legacy of The Heritage Group, our parent company. With nearly 90 years of experience in infrastructure, environmental services, and specialty chemicals, one of THG’s values is ‘creating enduring value’, and the group has been designing and operating resilient systems since long before it became a buzzword.

That history gives HG Ventures a unique perspective on what durability and long-term operational viability really look like—and how to evaluate it in emerging startups.

It also means our support goes beyond capital. We bring operational know-how, industrial scale-up experience, and real-world pilot environments that help young companies test and refine their technologies under realistic conditions. Resilience isn’t just something we invest in—it’s something we help build.

Where We Go From Here

As climate risks, geopolitical shocks, and economic uncertainty continue to shape the landscape, resilience will only become more valuable. Investors will need to ask harder questions about how startups will perform under stress. Founders need to design for longevity, not just launch.

For us, the next generation of hardtech and industrial innovation will be defined not just by what works, but by what endures.

News & Views arrow
March 11, 2024

Pitch Perfect: A Guide for Young Founders Presenting to VCs

The process of securing investment for a startup can be daunting, especially for young or first-time founders. The newest and youngest member of the HG Ventures team, Erin Crowther offers guiding principles on how entrepreneurs in this position can focus on generating the most value and investor interest in these high pressure situations.

Erin Crowther, Analyst at HG Ventures

Let’s make one thing clear right from the start: I’m no expert. I have only been in the world of venture capital for a short period of time.

But I do know what it’s like to be the youngest person in the room, surrounded by individuals with a variety of impressive startup and industry experience themselves, something that can be intimidating to young or first-time founders.

And while I am certainly not claiming to have all the answers when it comes to pitching a VC (I’m not even sure I have all the questions yet), I can offer advice based on the numerous pitches I have seen.

As a general guiding principle, entrepreneurs should be thinking: “What is the key information I need to communicate, to generate interest and keep the conversation going?”

Given the blizzard of information at hand, this can be a challenging task. And while each fund may have a slightly different investment process, the information presented below can serve as a guideline to those looking to maximize value in that initial conversation:

1. Know Your Audience

Before stepping into the meeting room, take the time to understand the goals and incentives of the VCs to whom you’ll be pitching. Are they corporate venture capitalists (CVCs) like HG Ventures or pure VC funds? Knowing their investment thesis and financial motivations is crucial.

At HG Ventures, for example, we primarily invest in technologies that are aligned with the industries in which The Heritage Group operates, as these are where we are most able to add value. Other CVCs are purely strategic investors, seeking to leverage synergies between the startup and their own business. And most VC funds have a sector focus. Who are you meeting? Tailor your pitch to demonstrate how your startup aligns with their interests–and how it can generate substantial returns.

2. Demonstrate Your Value Proposition

Clearly articulate the value proposition of your product or service in a concise and compelling manner. It is surprising how many technical founders struggle with this, usually because they are just too close to the subject matter. VCs are unlikely to be experts in your industry, so it is essential to communicate in clear terms how your solution addresses a pressing need and offers significant market potential.

A key reason why many startups fail is because of a lack of product-market fit. So while your product many have substantial product-feature advantages, it is critical to communicate the economic incentives that differentiate your offering. Is your product at cost-parity? Are you helping realize cost efficiencies elsewhere? Are you solving a supply chain problem? This allows investors to understand what’s driving your customers’ purchasing decisions. As a general rule, most VCs, whether pure VC or CVC, are financially driven, so unless you can demonstrate that there is a willing-to-pay market for your product it will be a lot harder to secure any kind of investment.

3. Highlight Traction

Actions speak louder than words. Provide tangible evidence of your startup’s traction and success to date. Whether it’s paid pilots, customer acquisitions, revenue growth, or strategic partnerships, concrete metrics validate your business’s potential and instill confidence in investors. What better way to demonstrate initial product-market fit than showing that people are willing to pay or partner with you?

Describing traction sets the stage for go-to-market and sales pipeline discussions. The early years of a startup’s life are filled with estimates, and traction is the foundation to helping us believe those multimillion-dollar revenue projections you are forecasting.

4. Emphasize Team Capabilities

As you set out to solve a problem and address an industry need, chances are there will be other people trying to do the same. Venture capitalists will be looking at the competitive landscape and placing their bet on who they believe will emerge as the market leader. Due to the variable nature of a startups’ early life, a large part of that bet relates to the team.

For a young or first-time founder, this can be more difficult given that you are ‘new to the game.’ If you lack previous startup experience, acknowledge it transparently and showcase your ability to surround yourself with the right talent. Be able to talk about what gaps are missing on your team, and how you plan to fill those gaps; this demonstrates a grasp of forward strategy.

5. Be Clear with Your Ask

The purpose of a capital injection is to accelerate development towards commercialization, so be crystal clear about your funding needs and the value-added milestones you aim to achieve with that investment. VCs appreciate entrepreneurs who have a strategic vision for their business’s growth and can articulate a clear roadmap for success. Whatever your funding stage, outline your capital requirements and how they align with your business objectives.

In addition to the financial ask, be clear about what your ask is from an investor expertise and strategic standpoint. The best VCs have much more to provide than capital; it’s important to know what other value they can add, and to ask for it.

6. Keep the Conversation Open

Remember, securing funding is never just about just one pitch meeting; no founder should expect that an investor will be prepared to write a check right away. I keep coming back to that guiding principle, that the goal should be to spark enough interest to keep the conversation going. This is not only important to remember in current investor discussions, but can be a crucial element to future capital raises. While an investor may choose to pass today, maintaining a positive rapport can lead to opportunities down the road.

Progressing through the diligence process, investors will be looking to learn more and more about your business in order to make an informed investment decision. All funds handle their investment processes differently and there is no single ‘right’ way of approaching things. That said, having a well-articulated and validated value proposition goes a long way.